October 29, 2026
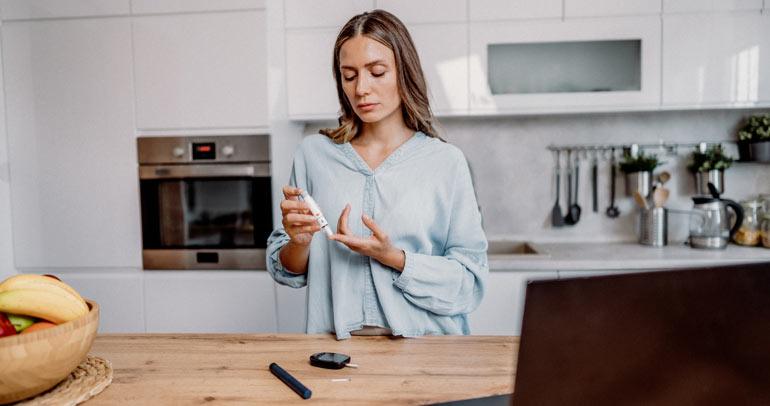
Food companies have already started responding to GLP-1 users. In February 2026, Reuters reported on manufacturers rethinking products and pack sizes. FoodNavigator has also examined how changes in eating and drinking reach other members of a user’s household.
What gets far less attention is what happens outside the home. Friends, colleagues and relatives of GLP-1 users make decisions together, then return to their own routines. Some of those routines are changing too.
One US respondent told us:
"The entire group (four people) almost entirely stopped going out to eat and drink together, because it's not an activity that we can all partake in. It's shifted our hangouts to other activities such as bowling."
US man, aged 18–24
Echo Consumer
At Escalent, we call these people Echo Consumers. They have never taken a GLP-1 themselves but know a current user and report changes to their own habits, shared occasions or both. We surveyed US and UK adults in August 2026 to understand the scale of this audience and the choices it is making.
Five Findings from Escalent’s Research
1. Counting GLP-1 Users Misses a Larger Group of Consumers
Around one in four US adults (24%) and one in five UK adults (21%) are Echo Consumers. The shares currently taking a GLP-1 are smaller: 14% in the US and 9% in the UK. That works out to 1.7 Echo Consumers for every current user in the US and 2.2 in the UK.
Most of this audience sits beyond GLP-1 households. In the US, 81% of Echo Consumers do not live with a current user. In the UK, it is 84%.
For a food manufacturer, retailer or restaurant group, those figures call for a wider view of demand. Research based only on current users and their households could miss a substantial audience whose choices and shared occasions are changing.
2. The Influence Can Become Personal
It is easy to notice when someone orders differently to accommodate a friend. A change in their own habits is harder for businesses to see.
Among Echo Consumers, 88% in the US and 89% in the UK report changes to their personal consumption or behavior. One respondent described it this way:
"It has changed slightly how I view food and the relationship with eating healthier for sure. I never thought about it a lot since I love food to begin with and seeing someone on GLP-1 made me take a step back."
US woman, aged 55–64
Echo Consumer
3. Sugary Snacks Are Losing Ground with Current Users and Echo Consumers
Current GLP-1 users are not the only ones cutting back on sugary snacks. In the US, 77% of current users report eating fewer, compared with 52% of Echo Consumers. In the UK, the figures are 80% and 47%. The reduction is greater among users, but the direction is the same for a sizeable share of Echo Consumers.
For snack brands, the question is whether people are reaching for treats less often or choosing something different. That distinction matters when deciding how to adapt product ranges, pack sizes and promotions.
It is worth testing whether familiar snacking occasions, pack choices and purchase triggers are changing across a wider customer base.
4. Echo Consumers Are Changing Their Own Drinking Habits
It’s not just food consumption that’s changing. More than one in four US Echo Consumers (27%) and a similar proportion in the UK (26%) say their own consumption of alcohol is reduced because someone they know is taking a GLP-1.
One respondent told us:
"I myself have started drinking less and started eating out less because of the diminished social pressure of doing so after my friend [GLP-1 user] stopped."
US man, aged 18–24
Echo Consumer
Alcohol consumption has been declining for some time. As The Drinks Business reported in June 2026, a third of British drinkers say they’re drinking less than a year ago, with some citing the influence of friends and family.
Escalent’s research identifies another influence on drinking habits. More than one in four US Echo Consumers (27%) and a similar proportion in the UK (26%) say they’re drinking less because someone they know is taking a GLP-1.
5. Echo Consumers Aren’t Just Cutting Back. They’re Exercising More and Consuming More Protein.
There are signs of growing activity as well. Among Echo Consumers, 42% in the US and 39% in the UK report doing more fitness or exercise. More protein consumption is reported by 39% and 38%, respectively.
Food, fitness and wellness brands should pay attention to these developing needs, not only to the categories where consumption is declining. New routines can create openings for products, services and experiences that fit how people now choose to spend their time.
The Market Definition Needs Updating
For a business forecasting demand, a count of current GLP-1 users is a starting point, not a market definition. Echo Consumers belong in the way companies segment shoppers, research purchase occasions and plan for category change.
That means finding out which Echo Consumers are changing decisions in a particular category, what prompts those changes and which products or experiences still earn a place. It is a more useful basis for innovation and planning than waiting for a shift to become obvious in sales figures.
How Escalent Helps
Escalent helps businesses understand changes that sit outside conventional market definitions. We specialize in helping clients navigate category disruption. Our Segmentation work can identify the Echo Consumer groups relevant to a category. Our Path-to-Purchase research shows who shapes a decision and when, while Opportunity Finder helps businesses test products, services and experiences against emerging needs.
ABOUT THE RESEARCH
Escalent surveyed 1,349 US adults and 1,602 UK adults in August 2026. Results were weighted to national population figures. The study identified 315 US and 335 UK respondents as Echo Consumers, people who have never taken a GLP-1, personally know a current user and report changes to their own behavior, shared occasions or both. Category figures exclude respondents for whom the category was not applicable. Current-user category figures describe changes since starting GLP-1 use; Echo Consumer figures describe changes attributed to knowing a current user. Quotations come from Escalent’s US and UK online and qualitative research.
Melissa Bane
Managing Director, Europe
Melissa oversees Escalent's European business and is responsible for driving growth for the company's vertical market practices across the region. She brings 25+ years of expertise in marketing, insights and consulting to client relationships and is passionate about growing profitable businesses. As Chief Storyteller and connecter of dots, she helps clients see the big picture and translate insights into action. A former technology entrepreneur, consultant, journalist and marketing head, she thrives in fast-moving, high-growth environments. Her superpower is finding intersection points across industries and mining opportunities therein. Much of her client work focuses on Consumer Goods and Retail and Technology. Based in London, she is a graduate of the University of New Hampshire, and unashamedly addicted to travel, yoga, gardening and Mexican food.